What Orlando Homeowners Need to Know Before a Wind Mitigation Inspection
A feature-by-feature guide for Orange County homeowners, with Citizens premium credit ranges and what your neighborhood's construction era means for your rating
A feature-by-feature guide for Orange County homeowners, with Citizens premium credit ranges and what your neighborhood’s construction era means for your rating
Central Florida’s peak hurricane risk runs August through October. If you’re an Orange County homeowner sitting on an outdated or nonexistent wind mitigation report, you’re running out of time to fix that before the season peaks. This is not a general preparedness lecture. It’s a guide to a specific document, filed on a specific state form, that can reduce your homeowners insurance premium if it accurately reflects what’s on and in your house.
Here’s what an inspector physically checks, what each item is worth in premium dollars, and what your neighborhood’s construction era almost certainly means for your rating.
Why Timing Matters Right Now
Orlando is not coastal, but that framing breeds a false sense of safety. Hurricane Charley caused serious damage across Orange County in August 2004, including roof failures in Dr. Phillips. Irma in 2017 brought destructive winds across the metro; Windermere and College Park reported widespread roof damage, downed trees, and structural losses. We tend to forget that quickly, and then the next storm reminds us.
The more pressing issue in 2025 is a wave of roofs replaced in the 2018–2020 period following Irma damage. Those roofs are now approaching seven years old. Citizens Property Insurance requires a current wind mitigation inspection on file, and under current Florida guidelines the report is valid for five years. Homeowners who had an inspection done alongside their Irma-era roof replacement are now at or past that window, and their premium credits may be at risk when Citizens reviews the report at renewal. That’s not a hypothetical. It’s a specific administrative problem with a specific deadline.
[Reporter’s note: Confirm the five-year validity period remains in effect for 2025–2026, as Florida HB 837 (2023) and any subsequent legislative changes may have affected this — check leg.state.fl.us.]
Citizens remains the dominant insurer for a large share of Orange County homeowners following the private market contraction of 2022 and 2023. A current, favorable wind mitigation report is one of the few direct tools homeowners have to reduce their Citizens premium. Most aren’t using it. Whether that’s because people don’t know the inspection exists, or because insurance paperwork is nobody’s idea of a good afternoon, the result is the same: money left on the table. For broader context on what Orange County homeowners are spending on coverage right now, our home & property coverage tracks these costs across multiple policy types.
Who Is Legally Qualified to Do This Inspection
“Wind mitigation inspector” is not a Florida license category. That distinction matters more than most homeowners realize. A report signed by someone without the correct underlying credentials will be rejected outright by Citizens and most private carriers. You’ll have paid for a document worth nothing and have to start over.
Under Florida Statute §627.711, the inspection must be performed by one of the following: a Florida-licensed general, building, or residential contractor; a certified building code inspector; a licensed home inspector with a wind mitigation endorsement; a licensed engineer; or a licensed architect.
[Reporter’s note: Confirm §627.711 language is current as of 2025 at leg.state.fl.us before publication.]
Before booking anyone, verify credentials at myfloridalicense.com, the Florida DBPR’s license lookup portal. Search by name or license number. Confirm the license type matches one of the qualifying categories above, that the status shows “Current, Active,” and check for any disciplinary history. This takes three minutes and should be non-negotiable.
A licensed general contractor who has done fifty wind mitigation reports is legitimate. Someone advertising “certified wind mitigation specialist” on a flyer without a verifiable Florida license is not. Those flyers are out there — I’ve seen them stapled to telephone poles in Milk District after every storm watch. Don’t call those numbers.
What the Inspector Is Actually Looking At
The inspection follows a standardized format. Every inspector in Florida uses the same form: the OIR-B1-1802, issued by the Florida Office of Insurance Regulation. This is not a pass/fail test, which surprises homeowners who expect a certificate at the end. The form records what physically exists in your home, and the insurer applies premium credits accordingly. A home that scores poorly in several categories still gets whatever credits apply to the features it does have.
The form covers eight main sections.
[Reporter’s note: Verify the current version of the OIR-B1-1802 at OIR.MyFloridaCFO.gov and confirm whether any revised form has been issued for 2025–2026.]
Roof Covering documents your roof type and age and confirms whether it meets the current Florida Building Code. A roof permitted and installed to the 2001 FBC or later receives credit.
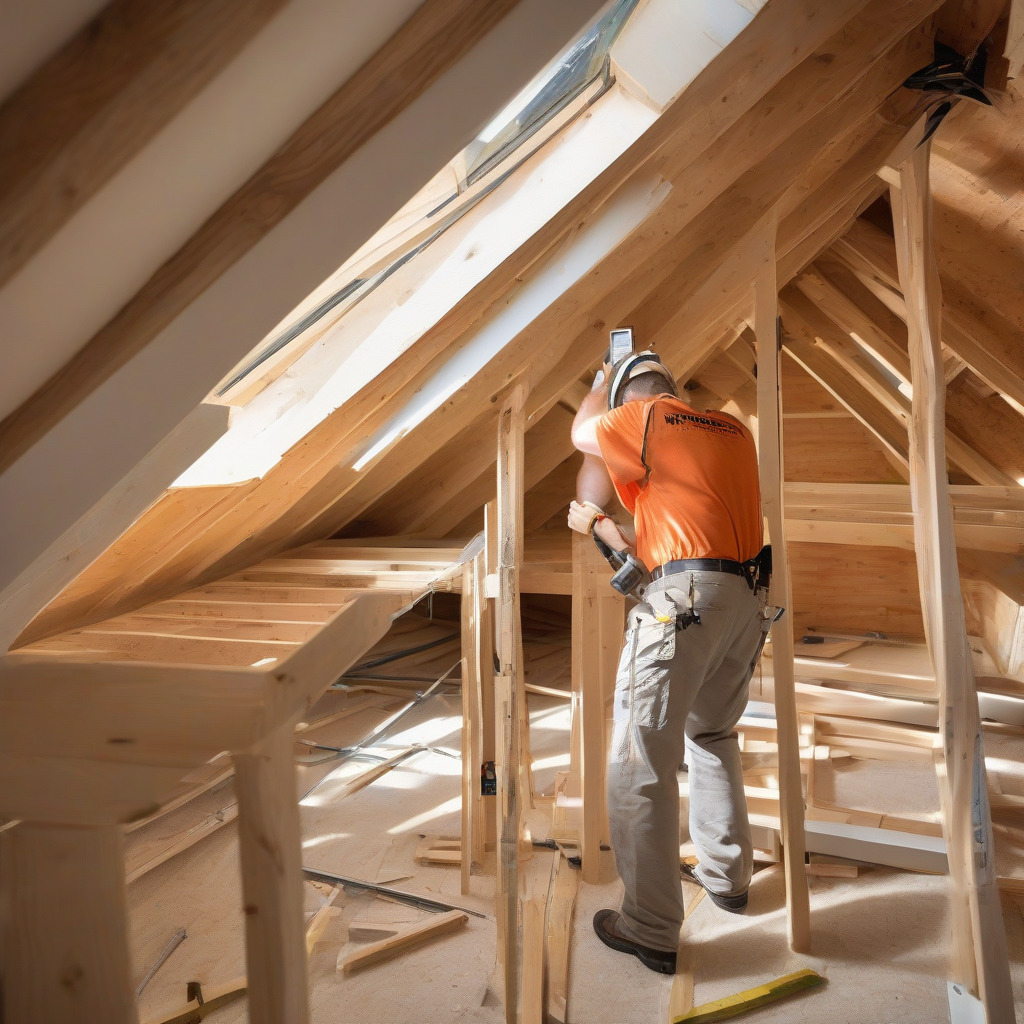
Roof Deck Attachment is where the inspector earns their fee. They go into your attic, pull back insulation, and physically examine the nails holding the plywood or OSB sheathing to your rafters — nail type, nail diameter, spacing pattern. An 8d ring-shank nail gets a stronger credit than a 6d smooth-shank nail; spacing also determines the credit tier. Many pre-1994 Orlando homes have lower-rated nailing patterns. That was standard construction before the Florida Building Code tightened post-Andrew. If your roof was replaced after 2002 with code-required ring-shank nails, you likely score well. But here’s the thing that surprises almost everyone: if your roof was replaced and the original deck boards were left in place, the inspector records the original nail pattern underneath. The new shingles don’t change what’s below them.
Roof-to-Wall Connection is the most consequential section for older Central Florida homes. More on this shortly.
Roof Shape — a hip roof, four sloping sides meeting at a ridge with no vertical gable ends, is more wind-resistant and earns a significant credit. A gable roof, the classic triangle-plus-vertical-wall shape common throughout older Central Florida neighborhoods, gets the lowest rating. Mixed configurations use a ratio calculation; the form has specific criteria for that.
Secondary Water Resistance refers to a layer of self-adhering peel-and-stick membrane installed between the roof deck and the shingles or tile. Its job is to keep water out if the primary roof covering fails. The inspector looks for evidence of this layer at the attic eaves or at any unsealed penetration. Older homes rarely have it. If your roofer installed standard felt paper rather than peel-and-stick underlayment, you don’t get this credit.
Opening Protection documents how your windows, doors, and skylights are protected against windborne debris. The hierarchy runs from no protection at the bottom, through basic shutters that meet some but not all code provisions, up to impact-rated protection — either impact-resistant glazing or shutters rated to the large-missile test standard. Full protection to the highest standard generates the largest single premium credit on the form. Partial coverage gets a proportionally reduced credit. That situation where you installed impact windows on the front of the house but still have the original single-pane sliders out back? The inspector notes it, and you don’t get full credit.
Building Code Compliance is largely documented through permit records rather than physical inspection. Construction or re-roofing to the 2001 Florida Building Code or later gets favorable treatment.
What Central Florida’s Housing Stock Usually Scores
Orange County’s housing stock divides into three construction eras with meaningfully different wind mitigation profiles. Knowing where your home sits in this timeline is probably the most useful thing you can do before booking an inspection.
Pre-1994 homes cover a large share of the housing in College Park, Conway, Pine Hills, Azalea Park, and the older sections of Winter Park. These were built before the changes triggered by Hurricane Andrew’s 1992 devastation of South Florida. Almost universally they have toe-nail connections at the roof-to-wall joint — the rafter or truss attached to the wall’s top plate using nails driven at an angle, no metal hardware. On the OIR-B1-1802, this scores at the lowest possible rating. These homes also typically have lower-rated deck attachment nailing, no SWR underlayment, and gable-end roofs. A pre-1994 College Park bungalow or Pine Hills ranch will often score poorly across multiple sections at once. No amount of fresh paint changes that, and it’s worth knowing before you’re surprised by a low-credit report.
Post-2002 construction in Horizon West, Lake Nona, Laureate Park, Waterford Lakes, and newer sections of Ocoee and Apopka was built under the Florida Building Code adopted in 2002 and strengthened in subsequent cycles. These homes typically have single-wrap or double-wrap hurricane straps — metal hardware wrapping over the top of the rafter and attaching on one or both sides of the wall framing — plus ring-shank nailing on the deck. Double-wrap connections became standard in post-2004 builds following that hurricane season. A Lake Nona home built in 2012 will often carry near-maximum mitigation credits already.
The 1994–2002 transition era is genuinely variable and requires inspection to know where you stand. Some homes have clips, some have upgraded nailing, and some were built under county-specific codes that varied before the statewide FBC was adopted. There’s no shortcut. You have to look.
For homeowners who want to do preliminary homework, the Orange County EPERMIT portal at epermit.ocfl.net lets you search by address and pull permit history, including roof permits with dates and contractor information. This won’t tell you the nailing pattern or connection type, but it confirms your roof age and gives you documentation the inspector may use to support the building code section of the form.
[Reporter’s note: Pull Orange County Property Appraiser data at ocpafl.org to confirm the approximate share of owner-occupied housing stock built before 1994; confirm with two or three working Orlando inspectors that EPERMIT access is part of their standard inspection practice.]
What Each Feature Is Worth on Your Citizens Premium
The discount schedule Citizens applies to favorable wind mitigation reports is published in the company’s underwriting manual. These are percentage reductions applied to the wind portion of the premium — and if you’ve renewed your Citizens policy lately, you know how large that bill has gotten. Our coverage of what Orlando homeowners are actually paying for property insurance in 2026 breaks down how wind premiums vary across Orange County ZIP codes.
A hip roof versus a gable roof generates a discount of roughly 25 percent on the wind premium. It’s a binary feature — you either have a hip roof or you don’t, and there’s no retrofit path short of major structural work.
The credit for double-wrap hurricane straps versus toe-nail connections runs up to approximately 30 percent of the wind premium. That’s the single biggest premium reduction available to older homes. Single-wrap clips score between toe-nails and double-wraps.
Full impact-rated opening protection — every window, every door, every skylight covered to the large-missile test standard — can generate up to approximately 45 percent of the wind premium in credits. Partial protection gets a proportionally reduced credit. The cost of impact windows and doors is substantial, but for homeowners who planned to upgrade eventually, the insurance math is worth running before assuming it doesn’t pencil out.
Deck attachment and secondary water resistance individually represent smaller credits, typically in the 5-to-15-percent range each, though I’d treat those figures as directional until confirmed against Citizens’ current rate filings. They’re additive with other credits and represent real money on a large base premium.
Citizens caps combined mitigation discounts and applies the rating algorithm in a specific order. The wind portion is also only part of the total premium. Anyone quoting you dramatic whole-premium reductions without spelling out that math is oversimplifying.
[Reporter’s note: Verify the dollar-value premium reduction range for a typical pre-1994 Orange County home with at least one independent Orange County insurance agent and against Citizens’ current rate filings before publishing specific figures. Also verify which private carriers are actively writing new homeowner policies in Orange County as of 2025 — Heritage Property & Casualty, Universal Property & Casualty, HCI Group, Slide Insurance, and Security First Financial have been cited as active; confirm with a FAIA member agent.]
The inspection itself costs a modest fee from Orlando-area licensed inspectors, and many bundle it with a 4-point inspection — required by many insurers for homes over 20 years old, covering roof, HVAC, plumbing, and electrical — for a combined fee. Ask about the bundle when you call around. They’re separate documents serving separate insurance purposes, but there’s no reason both can’t get done in one visit.
[Reporter’s note: Obtain verified pricing from at least two named, licensed Orange County inspectors before publishing specific figures.]
Your Roof Was Just Replaced — Why Your Rating May Not Have Changed
This is the most persistent misconception among Orlando homeowners who’ve been through a post-storm re-roofing, and it’s costing people real money.
A new roof does improve some sections of the wind mitigation form: roof covering type and condition, potentially deck attachment nailing if the contractor re-nailed with ring-shank fasteners, and secondary water resistance if they installed peel-and-stick underlayment. If your contractor did all of that and you have the documentation, a fresh inspection can reflect those improvements.
What a new roof does not touch is roof-to-wall connections. Unless the contractor specifically went into your attic and installed hurricane straps at every rafter-to-wall joint — which is not standard procedure in a typical re-roofing job, must be explicitly contracted and paid for separately, and adds real cost — your old toe-nail connections are still there. Still photographed by the inspector. Still rated at the lowest tier. A re-roof permit confirms the roof happened. It says nothing about the attachment hardware in the attic framing. Insurers and inspectors know this, which is why a permit alone doesn’t trigger re-rating on that section. It feels like it should. It doesn’t.
Homeowners who replaced their roofs in 2018 or 2019 after Irma and never had a subsequent wind mitigation inspection are almost certainly paying rates that reflect none of the improvements they made — not the new roof covering, not any better deck nailing, not any SWR underlayment. Booking an inspection is the only way to capture those credits.
If you’re planning a replacement now, get the contractor to document the specifics in writing before the crew leaves: nail type, diameter, and spacing used on the deck; the underlayment product name and spec sheet; whether any hurricane strap upgrades were performed and on how many connection points. Easy to get in the moment, nearly impossible to reconstruct six months later. If you can arrange attic access during or immediately after the job, an inspector can verify connections while the framing is actually visible.
[Reporter’s note: Confirm whether Florida statute or Citizens underwriting policy requires homeowners to proactively notify the insurer of a roof replacement to trigger re-rating, or whether re-inspection is entirely homeowner-initiated — check Florida Statute §627 or consult a Florida insurance attorney.]
What to Expect on Inspection Day
Get at least two quotes from licensed Orange County-area inspectors. Verify the Florida license before booking, not after.
Attic access is non-negotiable. The roof-to-wall connection and deck attachment sections require direct visual inspection of the framing. An inspector who skips your attic isn’t doing the inspection. Clear the path to your attic hatch before they arrive — it’s a small thing that people consistently forget until the inspector is standing in the hallway. They’ll also need exterior access to photograph the roof surface and document windows and doors. Pull together whatever documentation you have: roofing permits, contractor warranties, impact window or door certifications with product approval numbers, any prior wind mitigation reports.
The Orlando inspection market gets backed up in late spring and early fall, tracking with homeowners scrambling around insurance renewals or post-storm anxiety. February through April is the sweet spot. Inspectors are available, they’re not buried in post-hurricane claim work, and you’ll have a current report on file before June 1. If you’re reading this in late summer or fall, book soon anyway. A report filed now beats one you keep meaning to get.
Once you receive the completed OIR-B1-1802, submit it to your insurance agent for re-rating. If your report reflects improvements over what’s on file, the adjusted premium should apply at renewal. If it’s the first report on file, the credit applies when you renew.
One final thing: if an inspector quotes your results before completing the form, or if the report arrives with no attic photographs and no nailing-pattern documentation, those are red flags. The form requires specific photographic evidence for each rated section. A legitimate report is a thorough document — not a one-page summary. If it looks thin, push back.
The inspection is a one-time cost. The credit, if your home earns it, repeats every year. For most Orange County homeowners with pre-2002 homes who haven’t been inspected in the last five years, that’s the whole story.
CityDesk Orlando covers local business and real estate issues for Orange County residents. This article is for informational purposes; consult a licensed Florida insurance professional for advice specific to your policy. Statute references and OIR form details should be confirmed at leg.state.fl.us and OIR.MyFloridaCFO.gov respectively.